Wholesaler Insurance Guide: Finding the Correct Cover
Wholesaler Insurance Guide: Finding the Correct Cover
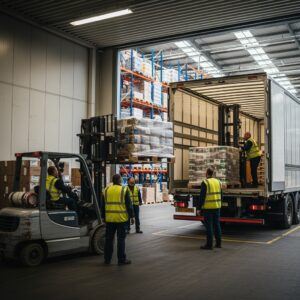
Running a wholesale business in the UK comes with unique challenges. From safeguarding stock to managing supply chains, your operations are constantly exposed to risk. That’s why having the correct wholesaler insurance is so important.
A strong policy doesn’t just act as a safety net—it protects your assets, minimises disruption, and supports long-term success. But with so many options available, how do you identify cover that truly matches the needs of your operation?
What is insurance for wholesalers?
Insurance for wholesalers is a specialised form of business insurance designed to address the risks unique to the distribution industry. Unlike generic policies, it takes into account issues such as stock damage, supply chain disruption, and third-party liability. Think of it as a tailored safety net that protects your business from multiple angles, allowing you to continue operations with confidence.
What does wholesaler’s insurance cover?
A comprehensive policy typically comprises several components, each designed to protect a distinct aspect of your business. Typical cover includes:
- Stock protection. This protects against fire, theft or accidental damage.
- Public and product liability. Shielding you against claims if products cause injury or damage.
- Business interruption. Maintaining steady cash flow when operations are disrupted.
- Property cover. Safeguarding warehouses, offices and equipment.
With these layers in place, you’re better equipped to withstand challenges that could otherwise have devastating consequences.
Why a wholesaler needs insurance
Running a wholesale operation means dealing with constant movement of goods, large stock volumes and tight supply chains. Each of these adds risk, from accidents and theft to delivery delays. Having robust insurance for your wholesale business ensures that you can absorb common risks and recover quickly.
Key types of insurance for wholesalers
Public liability insurance
This is your first line of defence against claims for injury or property damage that may occur on your premises or because of your operations. For wholesalers who regularly deal with clients, suppliers or the public, this cover is essential.
For example, if a visitor trips over a box in your warehouse, public liability insurance would cover the legal costs and any resulting compensation. From a large business to a small business, including sole traders, it’s a vital part of your insurance policy.
Product liability insurance
Wholesalers distribute large volumes of products, and if such goods cause harm or injury, your business could face substantial claims. Product liability insurance protects you against legal defence costs and compensation related to defective products.
Without this cover, a single claim could put your business operations at risk. With it, you have a financial shield that ensures your business can continue trading with confidence.
Employers’ liability insurance
If you employ staff, this cover is a legal requirement in the UK. It protects against claims from employees who suffer illness or injury in the workplace, along with associated legal expenses.
Employers’ liability insurance not only keeps you compliant but also highlights your commitment to staff welfare—something that can strengthen morale and workplace culture.
Business interruption insurance
Fires, floods or other unexpected events can halt operations overnight. Business interruption insurance helps bridge this financial gap by covering lost income and ongoing expenses, including salaries, rent, and loan repayments.
For wholesalers, where cash flow is crucial, this coverage ensures you can recover quickly and focus on rebuilding.
Property insurance
Your premises, stock and equipment are the backbone of your business. Property insurance protects these assets against risks such as fire, theft or natural disasters.
By covering repair or replacement costs, property insurance ensures that unforeseen damage doesn’t derail operations. For wholesalers holding large volumes of stock, it’s an indispensable part of risk management. Getting your property valued will help avoid underinsurance.
Evaluating cover options for wholesale goods
Goods insurance
Goods insurance comes in different forms, each designed to safeguard specific risks. For wholesalers, common types include:
- Comprehensive goods insurance. Covers stock against fire, theft or accidental damage.
- Goods in transit insurance. Ensures protection while your goods are being transported, whether between warehouses, to retailers or directly to clients.
By matching policies to the vulnerabilities of your stock, you can maintain supply chain integrity and minimise financial losses if the unexpected happens.
Assessing stock value
Accurate stock valuation is essential to avoid underinsurance. If your stock is undervalued, your policy payout may fall short in the event of a claim. Regular assessments, supported by professional appraisals where necessary, ensure your coverage accurately reflects the actual value of your inventory.
Matching cover to your needs
Not all wholesale businesses face the same level of risk. A tailored approach ensures you’re not paying for unnecessary cover while still safeguarding your most valuable assets. Seasonal fluctuations, specialist product ranges and business growth should all be factored into periodic reviews with your insurer or broker.
Business insurance for wholesale services
Goods aren’t the only assets worth protecting. Many wholesalers also provide services such as logistics, packaging or storage. These business activities add another layer of potential hazards that require dedicated cover.
Tailored insurance for service-based operations helps protect against liabilities tied to service failures or interruptions. By aligning cover with your service offering, you maintain client satisfaction and safeguard business reputation.
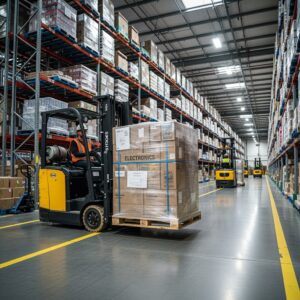
Comparing costs and finding value
The cost of wholesaler insurance depends on factors such as business size, location, risk profile and claims history. While comprehensive cover is essential, there are ways to optimise value:
- Implement risk management strategies to lower premiums
- Bundle policies for cost efficiency
- Please review the cover regularly to ensure it aligns with your business needs
Working with an experienced broker, such as Greenfield Insurance, can help you strike the right balance between affordability and protection.
Common pitfalls and how to avoid them
Too often, businesses fall into traps such as overlooking key coverage areas, misunderstanding policy terms or becoming underinsured. Each of these can leave your operations dangerously exposed.
Regular reviews, a clear understanding of policy language and accurate asset valuations are the best safeguards. Partnering with a reputable broker adds an extra layer of protection, ensuring your coverage is comprehensive and up-to-date.
Making a claim
If the worst happens, knowing how to make a claim is just as crucial as having cover in the first place. Always notify your insurer promptly, provide accurate documentation and keep clear records of any incidents. Photographs, witness statements, and organised paperwork strengthen claims and expedite resolution.
Efficient communication with your insurer or claims handler is key to getting your business back on track quickly.
Future-proofing your business
Commercial insurance isn’t static. As your business grows, your insurance coverage should adapt accordingly. Scalable solutions allow you to expand with confidence, while staying informed about regulatory updates and market trends ensures your cover remains relevant.
Ultimately, insurance for wholesalers is more than compliance—it’s about building resilience, maintaining trust and ensuring your business can weather any storm.
Conclusion
Securing the right insurance cover for your wholesale business is both a wise investment and a necessity. From protecting stock and premises to covering services and staff, the right policy provides a foundation for long-term stability. By understanding your risks, tailoring your coverage, and working with a reputable provider like Greenfield Insurance, you can focus on what matters most—growing your business with confidence.
Frequently asked questions
What insurance does a distributor need?
Distributors typically require a combination of public liability, product liability, and stock insurance. Employers’ liability is mandatory if you have staff, while business interruption cover can protect cash flow if operations are disrupted. The exact mix depends on the size of your business and the nature of your goods, so it’s best to seek tailored advice.
What is wholesale insurance?
Wholesale insurance is designed specifically for businesses that purchase goods in bulk and resell them to other businesses. It protects against risks such as stock damage, product liability and supply chain disruption. Many policies also include goods in transit cover, ensuring your stock is protected from the warehouse to the retailer.
What’s the difference between wholesale insurance and an MGA?
An MGA (Managing General Agent) is not a type of cover but a specialist insurance intermediary with authority from insurers to underwrite policies and manage claims. Wholesale insurance refers to the actual product designed for wholesalers, while MGAs are often the experts who arrange and manage it.
