Understanding Manufacturing Insurance: A Guide for UK Manufacturers
Understanding Manufacturing Insurance: A Guide for UK Manufacturers
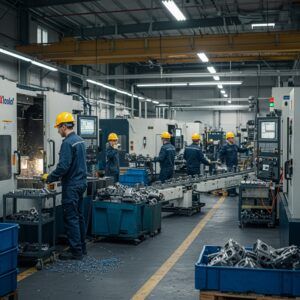
Manufacturing is a fast-moving and unpredictable industry, where even minor setbacks can carry a hefty price. That’s why insurance for manufacturers is more than just a safety net, it’s a crucial part of keeping production on track. From machinery breakdowns and supply chain delays to liability claims and damaged stock, the risks are as varied as the goods being made.
Whether you’re building cars, assembling electronics or producing food, the right cover can protect your business against financial loss and give you the confidence to plan ahead.
Manufacturing insurance topics:
- Product liability, business interruption, and property insurance are key types of cover for manufacturers.
- Insurance enhances credibility with clients and partners, boosting business reputation and trust.
- Manufacturing insurance is a vital tool for protecting your business against unique industry risks.
- Risk management through insurance solutions provides peace of mind and financial stability.
What is Manufacturing Insurance?
Manufacturing insurance is an essential part of managing risk in today’s competitive industrial landscape. No two businesses face exactly the same challenges, which is why cover is designed to protect against the specific risks that come with production, from safeguarding valuable machinery and stock to dealing with liability claims and business interruptions.
At its heart, manufacturing insurance provides protection against the kinds of setbacks that could halt operations or threaten profitability. Property damage, equipment breakdown, supply chain disruption and even product recalls can all be covered, with policies tailored to suit the scale and nature of each business. For UK manufacturers, that flexibility is crucial in an industry where margins are tight and downtime can be costly.
Rather than a one-size-fits-all product, insurance for manufacturers is best viewed as a safety net that can be built around your particular needs. Whether you operate a large-scale factory or a specialist workshop, the right policy not only protects physical assets but also helps safeguard reputation and financial stability.

Types of insurance cover for a manufacturing business
Each type of insurance serves a specific purpose, ensuring that your business is protected from various risks inherent in the manufacturing industry.
Product Liability Insurance for Manufacturers
Product liability insurance is a cornerstone of risk management for manufacturers, offering vital protection when products cause injury or damage. No matter how rigorous your quality control processes may be, defects can still occur, and the financial and reputational consequences can be significant.
This type of cover steps in to handle legal fees, compensation claims, and even the costs of product recalls, ensuring that a single incident doesn’t derail your business. Beyond financial protection, it demonstrates to customers that you take responsibility for the safety of your products. In doing so, it safeguards not just your balance sheet, but also your reputation.
Choosing the right policy begins with understanding the specific risks associated with your products. Working with the insurance specialists at Greenfield Insurance allows you to identify potential vulnerabilities and select cover that matches your needs. This proactive approach ensures your operations are protected against unforeseen setbacks, keeping your business resilient and your reputation intact.
Business Interruption Insurance for Manufacturers
Business interruption insurance is a vital safeguard for manufacturers, providing financial support when unforeseen events bring operations to a halt. From fires and floods to equipment breakdowns, even short-term disruptions can have a significant impact on production lines and, ultimately, the bottom line.
This type of cover ensures that lost income is replaced during periods of downtime, allowing businesses to continue meeting essential expenses such as payroll, rent, and loan repayments. By maintaining this financial stability, manufacturers are better positioned to recover quickly and minimise the long-term effects of disruption.
For many businesses, the importance of business interruption insurance goes beyond simply covering lost revenue. Comprehensive policies can also extend to supply chain interruptions — a critical issue in modern manufacturing where delays or shortages can jeopardise production schedules and customer commitments. By safeguarding against these risks, the right policy helps manufacturers maintain continuity, protect relationships with clients, and preserve their reputation for reliability.
Property Insurance for Manufacturers
Property insurance is a fundamental safeguard for manufacturers, protecting the physical assets that keep your business running, from buildings and machinery to stock and raw materials. With so much capital tied up in these assets, any damage or loss can have far-reaching consequences for production and profitability.
This type of cover protects against a wide range of risks, including fire, flooding, theft, and vandalism. By ensuring that repairs or replacements are funded quickly, property insurance helps minimise downtime and keeps your operations on track. For many manufacturers, it is not simply about recovering from disaster, but about maintaining continuity and confidence in the face of unexpected events.
Ultimately, property insurance is not just about protecting buildings and equipment — it is about safeguarding the stability and future of your business.
Public Liability Insurance for Manufacturers
Public liability insurance is a cornerstone of any manufacturer’s risk management strategy, offering protection against claims made by third parties for injury or damage linked to your operations. Whether it’s a customer slipping on-site or accidental damage to a visitor’s property, the costs involved in defending such claims — and paying compensation if required — can be substantial.
This cover ensures your business isn’t left exposed to crippling legal bills or financial settlements. Just as importantly, it demonstrates professionalism and responsibility, qualities that can strengthen your reputation within the industry and among customers.
For manufacturers who engage directly with the public, suppliers, or contractors, public liability insurance provides peace of mind that your business can withstand unexpected claims while continuing to operate with confidence.
Employers’ Liability Insurance for Manufacturers
Employers’ liability insurance is a legal requirement for all manufacturing businesses in the UK. It provides vital protection against claims made by employees who suffer work-related injuries or illnesses, covering both legal costs and compensation payments. Without it, businesses not only risk heavy financial penalties but also potential closure for non-compliance.
Beyond its legal necessity, this cover reflects a manufacturer’s commitment to employee welfare and safety. By ensuring your workforce is protected, you demonstrate responsibility as an employer, something that can boost morale, foster loyalty, and improve productivity.
Of course, prevention remains as important as protection. Regular health and safety audits, training, and proactive risk management can help reduce the likelihood of accidents. However, even in the safest environments, unforeseen incidents can occur. Employers’ liability insurance ensures that when they do, your business is safeguarded against significant financial losses.
Managing Risks with Insurance Solutions
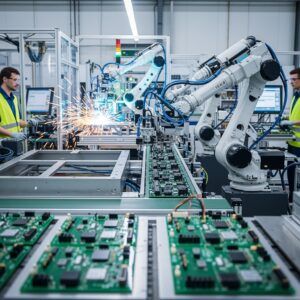
Risk management is a fundamental aspect of running a successful manufacturing business. It begins with identifying potential threats to your operations and implementing strategies to mitigate them. Insurance solutions offer a vital safety net, protecting your business from a wide array of risks.
Understanding the common risks faced by manufacturers is the first step in managing them effectively. Whether it’s equipment failure, supply chain disruptions, or liability claims, knowing these risks allows you to select the right insurance solutions. Tailored insurance policies can address specific vulnerabilities, providing comprehensive protection for your business.
Regularly reviewing your insurance cover is crucial to ensure it meets your evolving needs. As your business grows and changes, so too do your risks. By staying on top of these developments, you can adjust your insurance policies accordingly, ensuring that you’re never caught off guard by new challenges. The Greenfield Insurance team are specialists and can help you navigate the complexities of the insurance marketplace.
Does manufacturer insurance include equipment breakdown insurance?
Insurance for manufacturers is usually sold as a package, combining essentials such as public liability, employers’ liability, product liability, and cover for buildings, contents and stock. But when it comes to protecting the machinery that keeps production moving, things aren’t always straightforward.
Machinery breakdown cover is not normally included as standard. Instead, it’s often treated as an optional add-on or a separate policy. It typically protects against sudden and unforeseen damage to key equipment , whether from electrical failure, mechanical faults, or operator error.
Many insurers also link machinery breakdown with business interruption cover, providing compensation if downtime halts production and affects income. For manufacturers, where even a short stoppage can be costly, this protection can be critical.
If equipment breakdown cover is beneficial to your business, a member of the Greenfield Insurance team will be happy to look into it.
Summary
In the intricate world of manufacturing, securing your business with the right insurance is not just prudent—it’s essential. From product liability to business interruption and beyond, each type of cover plays a pivotal role in protecting your operations, assets, and reputation. By understanding the nuances of manufacturing insurance and working with specialists, you can tailor a comprehensive risk management strategy that safeguards your business’s future.
Manufacturers insurance FAQ
What insurance is legally required for manufacturers in the UK?
If you employ staff, you must have Employers’ Liability Insurance under UK law. This protects your business against claims from employees who suffer injury or illness at work.
What cover is typically included in a manufacturers’ insurance policy?
Most policies combine key protections such as public and product liability, employers’ liability, cover for buildings, machinery and stock, business interruption, and goods in transit. These are often packaged into a Commercial Combined policy.
Are there optional extras I should consider?
Yes. Many insurers offer add-ons including machinery breakdown, product recall, cyber cover, environmental liability, and engineering inspections. These can be tailored to your risks.
What’s the difference between public liability and product liability?
Public liability protects you if a member of the public is injured or their property is damaged because of your business activities. Product liability specifically covers damage or injury caused by products you’ve manufactured, supplied or sold.
Does insurance cover machinery and equipment?
Standard policies protect against fire, theft, flood and accidental damage. For mechanical or electrical breakdowns, specialist equipment breakdown cover is usually required.
How does business interruption insurance work?
If an insured event, such as fire or flood, forces you to halt production, business interruption insurance helps cover lost income and ongoing costs while you recover.
Will my insurance cover goods in transit?
Most policies can include goods in transit cover, which protects items being transported by road, sea or air.
How much does manufacturing insurance cost?
Premiums vary depending on factors such as your turnover, workforce size, equipment, materials used, claims history and location.
How quickly can I get covered?
Straightforward policies can be arranged in a few days, but complex operations may take longer while insurers assess your risks.
How can I reduce insurance costs?
Working with a specialist broker like Greenfield Insurance, consolidating policies, maintaining robust safety standards, and paying annually rather than monthly can all help keep premiums down.
What are the most common claims in UK manufacturing?
Frequent claims include property damage, employee injuries, equipment breakdowns, and product liability issues. Good maintenance, staff training and quality controls can help reduce these risks.
Does manufacturers’ insurance include cover for a product recall?
Standard manufacturers’ insurance policies in the UK don’t usually include product recall as part of their core cover. For that, you’ll need dedicated product recall insurance.