What is Underinsurance and Why is it Such a Threat?
What is Underinsurance and Why is it Such a Threat?
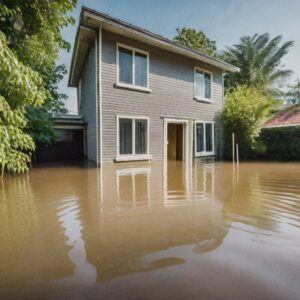
Underinsurance is a silent threat lurking in the shadows of many UK households & properties. A recent report published by a RICS-regulated valuation company established that nine out of ten UK properties have insurance levels set to an incorrect amount, and 76% of UK properties are underinsured.
Property rebuilding costs have spiralled over the last few years due to, in part, significant world events such as COVID-19, the Russia-Ukraine war, and Brexit. This has resulted in massive increases in material costs and labour rates, leaving a considerable percentage of properties underinsured and at high risk of a claim being reduced or declined.
This guide aims to illuminate the concept of underinsurance, dissect its implications, debunk myths, and offer practical advice on protecting your most valuable assets.
Key Topics
• What is underinsurance
• How to set the sum insured (also known as the declared value)
• What’s the difference between building insurance and contents insurance
• The importance of having adequate contents insurance
• Tips for assessing the level of contents insurance needed
• Case studies
• Summary
• Frequently asked questions
What is underinsurance?

Many UK individuals or businesses mistakenly assume that their policies automatically cover the full value of their properties when it comes to home or buildings insurance. This assumption often leads to underinsurance, a situation where the insurance cover falls short of the property’s actual rebuild cost.
Underinsurance occurs primarily because many people underestimate values. They might base their insurance on an outdated market value or the initial purchase price of the property, ignoring any renovations, improvements or market changes. As a result, when they file a claim, they find themselves with cover that doesn’t match their needs.
Regular reassessment of your insurance policy is crucial—it’s not just about having cover but having the right.
How to set the sum insured (also known as the declared value)
Insurers may reduce a claim settlement proportionately if a property is found to be underinsured following a damage claim. This is known as the application of average or average clause.
For example:
The building is insured for £400,000
Insurers calculate the rebuilding cost to be £800,000
The insurance claim totals £150,000
With the application of average, insurers will only pay 50% of the claim, or £75,000, leaving the policyholder £75,000 out of pocket.
However, in a worst-case scenario, under the Insurance Act 2015, an insurer may consider that the declared rebuilding sum insured represented a deliberate or reckless breach of a policyholder’s duty and would, therefore, be within their rights to decline the claim and void the policy, meaning that the claim would be unpaid. Typically, this is where a building is significantly underinsured (usually by more than 50%)
Therefore, a building’s sum insured must be correct to minimise risk in the event of a claim.
One common misconception is that standard insurance policies automatically cover the building’s full rebuilding cost. This is not the case as policies will only pay up to the declared value or sum insured.
Find out more about average and underinsurance here.
What’s the difference between buildings insurance and contents insurance
Understanding the difference between buildings insurance and contents insurance is vital to ensuring complete protection for your home. Buildings insurance covers structural elements, such as walls, roofs, and floors, while contents insurance covers personal items within the home. Homeowners need both types to protect their investments and belongings adequately.
The importance of having adequate contents insurance

This type of insurance is essential for ensuring your possessions are covered against loss or damage. Another myth is that contents insurance automatically covers all personal belongings. In reality, there are often limits on individual items, which means that high-value items like jewellery or electronics may not be fully covered. Many may assume that cover is adequate after years of paying premiums. However, without regular updates to reflect changes in the property’s value or contents, some may find themselves underinsured.
Tips for assessing the level of contents insurance needed
Begin by making an inventory of all your personal belongings, including high-value items like jewellery or electronics. This inventory will provide a precise estimate of the total value of your possessions, helping you determine the appropriate level of contents insurance. Keep receipts and valuations for high-value items, as these documents can aid the claims process if items are lost or damaged.
Review and update your contents list regularly to account for new purchases or changes in your lifestyle. Consider potential risks, such as theft or natural disasters, and adjust your cover accordingly. The average clause in insurance policies means that being underinsured can result in reduced payouts, so it’s essential to have enough coverage to match the value of your belongings.
Understanding the value of your contents involves knowing the replacement cost, not just the purchase price, of your items. This means considering both the sentimental and monetary value of your possessions. Stay informed about insurance limits for individual items, as some policies may have caps on coverage for specific belongings.
Case Studies: Underinsurance in the UK – Small and Medium-Sized Enterprises (SMEs)

Company: A family-owned retail business in London.
Industry: Retail (Selling home appliances)
Size: Small business with ten employees
Revenue: £500,000 annually
Situation analysis
The business operated from a leased storefront, with inventory valued at around £150,000. The owners had initially taken out a commercial property insurance policy, which provided £100,000 in coverage. While this provided some level of protection, the business was not adequately insured for the full value of its inventory or the potential risks it faced. The owners also had business interruption insurance, but the policy only covered six months of lost revenue, even though their Insurance Broker recommended at least a year’s coverage for retail stores.
The owners chose the lower coverage limit to save on premiums, not fully understanding the financial risks of underinsurance. They were unaware that in the event of a partial loss, the insurance company would apply an “average clause,” which proportionally reduces the payout for losses if the business is underinsured.
Incident: Electrical fire
In early 2023, an electrical fault led to a fire in the building. While the building was only partially damaged, the fire destroyed a significant portion of the inventory and required extensive renovations. Additionally, the business had to close for repairs and lost revenue due to the closure.
Financial impact
1. Inventory loss: The fire destroyed £90,000 worth of inventory.
a. Insurance payout: Since the business was underinsured (with only £100,000 instead of £150,000 coverage), the average clause was applied. The insurance company only covered two-thirds of the inventory loss (i.e., £60,000 out of £90,000), leaving the business with a £30,000 shortfall.
2. Property repairs: The building required £60,000 in repairs, of which the insurance covered only £40,000 due to the same average clause application.
3. Business interruption: The six-month business interruption insurance was insufficient. While repairs and restocking took eight months, the business received revenue loss compensation for only the first six months, creating a two-month revenue shortfall. Given their average monthly revenue of £40,000, this amounted to an additional financial burden of £80,000.
Total shortfall: £30,000 (inventory) + £20,000 (repairs) + £80,000 (interruption) = £130,000
Outcome and lessons learned
The business struggled to recover from the losses. The owners had to take out loans to cover the shortfall, increasing their debt burden and putting the business at risk of closure. It took two years for the company to fully recover financially from this event.
This case illustrates several common causes and consequences of underinsurance for SMEs:
• Risk underestimation: The business did not fully assess the value of its inventory or the time required to resume operations after a loss. This oversight led to inadequate coverage limits.
• Cost-saving decisions: Lower premiums can be tempting, but they often mean accepting higher risks.
• Awareness gap: Many small business owners are unaware of the average clause and how it affects claims for underinsured businesses.
Key points for UK businesses
1. Evaluate asset value regularly: Business owners should review their inventory, property, and assets annually to ensure adequate coverage.
2. Understand policy details: Familiarity with terms like the average clause and the implications of business interruption coverage is critical for making informed decisions.
3. Consult insurance advisors: Professional brokers, such as Greenfield Insurance can help small business owners understand the specific risks in their industries and avoid underinsurance.
Summary
Underinsurance is a significant risk for UK residents and SMEs, especially in sectors with physical assets like retail. This case demonstrates that the cost savings from lower premiums can ultimately lead to financial strain if a business cannot adequately cover losses. By understanding and addressing underinsurance, UK businesses can better safeguard their operations, continuity, and financial stability in the event of unforeseen losses.
Underinsurance FAQs
What is the meaning of underinsurance?
Underinsurance is when you do not have enough insurance coverage to fully replace or repair your property in case of loss or damage.
Can I use an online rebuild cost calculator to check for underinsurance?
Yes, online calculators are available along with surveyors who will undertake an on-site review, please contact us for further information
What level of buildings insurance do I need?
It’s important to assess the level of cover you require. This can only be achieved with an up-to-date rebuild cost.
What does it mean to be underinsured?
Being underinsured means that your insurance coverage is insufficient to cover the full cost of replacing or repairing your property after a loss or damage occurs.
What happens if I am underinsured?
If you are underinsured, you may have to bear some out-of-pocket costs when making a claim. This can lead to financial strain and may hinder your ability to recover from the loss or damage fully.
To mitigate the underinsurance risk or have a member of our dedicated team look into a policy, please contact Greenfield Insurance.